

SAVYINT Among Vietnam’s Top 10 Tech & Map 2026 in Digital Trust and Digital Finance
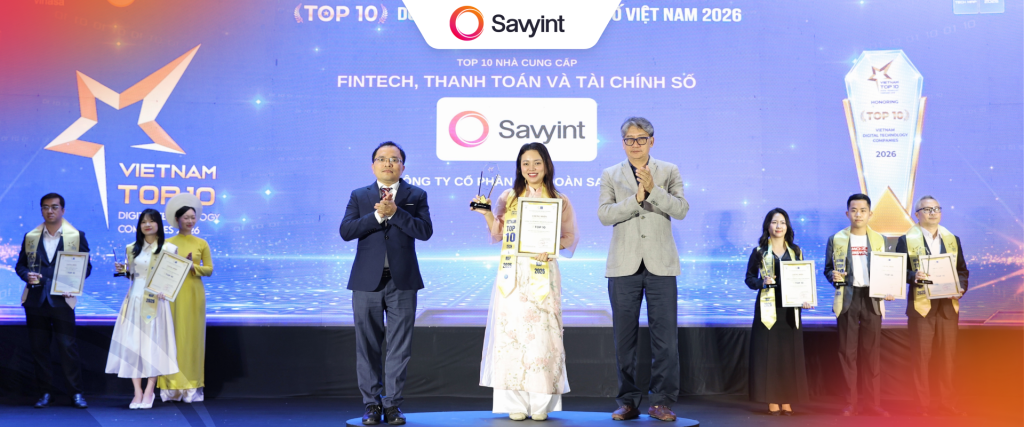
SAVYINT has been recognized in Vietnam’s Top 10 Tech & Map 2026 across two strategic categories: Information Security, Digital Trust & Resilience Providers; and Fintech, Payments & Digital Finance Providers, affirming its technological capabilities and commitment to advancing secure digital innovation. On November 18, 2026, at the announcement ceremony for the Vietnam Top 10 Digital Technology Companies 2026, organized by the Vietnam Software and IT Services Association (VINASA), Savyint was recognized in two key technology categories. This recognition acknowledges Savyint’s ongoing efforts in research, the development of core technologies, the expansion of its product ecosystem, and the delivery of technology solutions to organizations and enterprises. Recognition in these two strategic categories further demonstrates Savyint’s capabilities in addressing increasingly demanding requirements for security, digital trust, connectivity, and innovation in financial services within the digital economy. Information Security, Digital Trust & Resilience Providers The growth of the digital economy is bringing increasingly stringent requirements for data protection, identity verification, transaction security, and the operational continuity of technology infrastructure. As cyber threats continue to grow in scale and sophistication, organizations and enterprises need solutions that go beyond system protection to enable proactive risk identification, security monitoring, and incident response. Throughout its development, SAVYINT has consistently aligned its solutions and operations with international regulatory frameworks, industry standards, and sector-specific compliance requirements across multiple markets. Key examples include the European Union’s eIDAS 2.0, NIS2, PSD2/PSD3, and GDPR; Malaysia’s Risk Management in Technology (RMiT) framework and Personal Data Protection Act (PDPA); and the Philippines’ Anti-Financial Account Scamming Act (AFASA), among other relevant regulations. With a strategic focus on comprehensive security and digital trust technologies, Savyint has developed an integrated ecosystem of solutions covering multiple layers of protection. These range from infrastructure security, cryptographic key management, and post-quantum data protection and storage to PKI, HSM, Zero Trust, digital signatures, and trusted timestamping platforms. Alongside these capabilities, SAVYINT develops a comprehensive portfolio of electronic identity and authentication solutions, including Digital Identity & Anti-Fraud, Digital ID Wallet, Decentralized Identity (DID), FIDO2, Smart KYC/KYB, and biometric and FIDO2/Passkey authentication. The integration of AI into fraud prevention and risk management further strengthens the ability to detect threats, verify identities, and protect users across digital environments: a. Digital Trust Fabric b. Data Security & Cryptography Suite SAVYINT incorporates international standards into its product development from the outset, ensuring alignment with global security and digital identity requirements and standards, including OAuth 2.0, OpenID Connect (OIDC), and OpenID for Verifiable Credentials (OpenID4VC). The company also aims to develop platforms compatible with the European Architecture and Reference Framework (ARF) for the European Digital Identity (EUDI) Wallet initiative. In particular, to build next-generation secure information and digital transaction infrastructure, SAVYINT is researching and developing quantum security technologies, Post-Quantum Cryptography (PQC), Quantum Key Distribution (QKD), and Quantum Communication. Through this integrated ecosystem, Savyint empowers organizations and enterprises to strengthen the protection of digital identities, data, and electronic transactions; enhance their capabilities in cybersecurity monitoring, threat detection, and incident response; and build secure, trusted, and highly resilient digital systems. Fintech, Payments & Digital Finance Providers The growth of Open Banking, Embedded Finance, and digital financial service models is driving significant transformation across the financial services and banking sectors. Within this evolving ecosystem, connectivity among financial institutions, technology companies, and third-party service providers has become increasingly important for expanding services, optimizing customer experiences, and enabling new business models. However, as connectivity and data sharing increase, financial institutions must also address more stringent requirements for transaction security, customer consent management, access control, and regulatory compliance. Consequently, digital finance development involves more than simply digitizing traditional products and services. It also requires an integrated technology infrastructure capable of managing data, connecting systems, and ensuring secure and transparent operations. By combining connectivity platforms, data management capabilities, and workflow automation, Savyint delivers solutions that help financial institutions and banks modernize their technology infrastructure, optimize operations, and accelerate the development and delivery of digital services: By driving open connectivity and the end-to-end digitization of financial processes, Savyint aims to help organizations unlock the value of data, develop new service models, and strengthen their competitiveness in an increasingly dynamic digital financial landscape. Highlights from the Vietnam Top 10 Tech & Map 2026 Ceremony:
SAVYINT Advances Mobile ID Wallet and Cross-Border Digital Trust Capabilities
SAVYINT Global is advancing its SAVYINT Mobile ID Wallet, powered by its core Digital Trust technologies and designed to enable citizens and businesses to verify their identities, receive, store and share digital credentials, and sign documents securely on their mobile devices. Built to support cross-border digital trust services, the platform is underpinned by TrustCA QTSP 2.0, with Tayllocox providing advisory, assessment and certification support for eIDAS 2.0 and NIS compliance. It aims to deliver the security and interoperability required by evolving international standards and the EU regulatory framework, including provisions taking effect from 1 January 2027. What sets the platform apart is three layers in a single app: citizen authentication through VNeID for every service offered in the wallet; a digital credential wallet built on the OpenID4VC High Assurance Interoperability Profile (HAIP), published by the OpenID Foundation in December 2025. As digital transformation accelerates, mobile-based digital identity and wallet solutions are becoming essential to providing secure, convenient, and seamless access to digital services. In response to this growing demand, SAVYINT is advancing its Mobile Identity & Digital Wallet platform, designed to bring digital identity, electronic credentials, and essential digital services together in a unified mobile experience. 1. SAVYINT Mobile ID Wallet: one platform, three layers of capability The platform provides every component a country, ministry or financial institution needs to run a complete digital credential ecosystem: 2. Full compatibility with international digital ID wallet standards SAVYINT Mobile ID Wallet is compatible with the following international standards, so credentials it issues or verifies work with other conformant wallets, issuers and verifiers, in Vietnam and abroad: Standard How the platform applies it OpenID4VCI Credential issuance into the wallet under OpenID for Verifiable Credential Issuance; presentation over OpenID4VP; aligned with the OpenID4VC HAIP profile ISO/IEC 18013-5 ISO mdoc format for mobile driving licences (mDL) and identity documents; in-person presentation over NFC, BLE and QR, even without a network SD-JWT VC IETF SD-JWT VC format for online transactions, with selective disclosure FAPI 2.0 Financial-grade security profile for every API between wallet, issuer and verifier; DPoP, PKCE S256 and ECDH-ES/A128GCM response encryption FIDO2 Passwordless authentication with device-bound passkeys (WebAuthn L3, CTAP 2.1) through SAM FIDO2 Identity Server CSC API v2.0 / v2.2 Cloud Signature Consortium remote-signing interface between the wallet and TrustCA QTSP eIDAS 2.0 Aligned with the EUDI Wallet architecture under Regulation (EU) 2024/1183; TrustCA QTSP certified by Tayllorcox (EU) under eIDAS 2.0 and NIS2 3. User experience: authenticate, store, share, sign The app is designed so that citizens can use it straight away without needing to understand the technology behind it. The journey has four steps: authenticate through VNeID, keep credentials in the wallet, share selectively when asked, and sign remotely with TrustCA. Sector Typical scenario Public services Authenticate through VNeID, file administrative procedures online without paper copies, and sign applications on the phone Digital banking Account opening, authentication of high-value transactions under Circulars 50/77, remote signing of loan agreements Credit information Consent-based sharing of credit data that the customer can revoke at any time Telecom Verified SIM registration, safe SIM replacement and protection against SIM-swap fraud Transport Show a digital driving licence to traffic police even offline; rail, metro and boarding passes Healthcare, education Hospital check-in with a digital health insurance card; instant verification of diplomas and certificates 4. Partnering with SAVIS to Advance the Super App Ecosystem SAVIS is a Vietnam-based technology company with extensive experience in developing and deploying digital trust, cybersecurity, and eGovernment solutions. Its capabilities span national-scale Public Key Infrastructure (PKI), mobile Digital Identity and Electronic ID (eID), Qualified Trust Services (QTSP), remote digital signatures, and Mobile PKI. SAVIS also provides advanced identity verification and authentication technologies, including FIDO2 and Passkey, biometric authentication, eKYC, and ID verification, alongside anti-fraud solutions such as SIM Swap detection and prevention. With a portfolio of products and solutions serving government agencies, financial institutions, and enterprises, SAVIS has also received international recognition, including the Asia-Pacific ICT Alliance (APICTA) Awards, ASOCIO Awards. Building on these capabilities, SAVYINT will work alongside SAVIS to integrate and deploy the Mobile Identity & Digital Wallet platform within the eGov Super App ecosystem. The collaboration aims to connect digital identity and wallet capabilities with VNeID and online public services, creating a unified mobile platform for citizens to access and use digital government services. Through this collaboration, SAVYINT and SAVIS seek to strengthen the digital identity infrastructure underpinning the eGov ecosystem, enabling secure identity verification, convenient access to digital documents, and seamless connections to public services. By combining SAVYINT’s expertise in Digital Identity, Authentication, and Digital Trust with SAVIS’s capabilities in eGovernment platforms and system integration, the two companies aim to advance a comprehensive Mobile Super App ecosystem, bringing identity, documents, and public services closer to citizens through a single digital experience. 5. Building the Future of Mobile Digital Identity With its SAVYINT Mobile ID Wallet, SAVYINT aims to contribute to the development of secure, interoperable, and user-centric digital identity ecosystems in Vietnam and internationally. Connect with SAVYINT to explore our SAVYINT Mobile ID Wallet solutions and discover opportunities to build integrated digital identity and service ecosystems.
Leveraging LTV Technology for Long-Term Electronic Archiving
For electronic archiving, Long-Term Validation (LTV) technology for digital signatures plays an indispensable role. LTV is understood as the process of validating electronic documents to ensure the validity of digital signatures at the time of signing, using Cryptographic Message Syntax (CMS) technology and advanced Public Key Infrastructure (PKI) formats. To use LTV, the system must accurately determine the signing time through an attached Timestamp. LTV is an important component of the advanced digital signature standard for PDF, known as PAdES. PAdES is defined as “a set of rules and additional features for PDF/ISO 32000-1 files designed to support advanced digital signatures.” While PAdES is the standard for applying and validating advanced digital signatures in PDF files, CAdES serves as a guiding standard for the technical specifications of advanced digital signature technology. Advances in digital signature technology for PDF files have become truly useful thanks to the support of new features. Currently, the PAdES digital signature profiles provided by Foxit PDF SDK include: What Is the Purpose of LTV? When signing a paper document by hand, the signatory generally assumes that the signature will remain valid indefinitely. The same assurance is required for electronic documents, even as technology continues to evolve. Without LTV, electronic documents are subject to limitations on how long they can be validated and may become invalid when the CA ceases to provide services. This can result in the costs of revalidating and re-signing electronic documents, as well as re-establishing signed contracts or legal instruments. Using digital signature technology that supports LTV enables users to electronically archive contracts, forms, and PDF documents with full legal validity. Today’s advanced technology allows users to attach multiple Timestamps and validation data to signatures within the same PDF file. This process can be repeated multiple times, extending validation capabilities through a chain of validation records, even after the original digital certificate has expired or been revoked. How Does LTV Benefit Electronic Archiving? Long-Term Validation (LTV) technology ensures the trustworthiness of digital signatures by preserving the signing time and using this information as a reference point for validation. This is far more practical than relying solely on a single CA or a particular clause in a contract or legal document. Documents signed digitally with LTV can be re-signed, and the new digital signatures can be validated without having to repeat the entire contract execution process or create new contracts, thereby reducing associated time and labor costs. Using LTV with the PDF/A Format By combining LTV technology with the PDF/A standard, a PDF format specifically designed for long-term archiving, users can maintain electronic archives of digitally signed documents with long-term validation capability for many years. This is an ideal choice for companies and organizations that use PDF/A to archive large volumes of electronic documents. LTV Compliance For companies and organizations subject to stringent regulations governing electronic records, particularly electronic contracts, LTV technology provides an effective solution. By implementing LTV, organizations and companies can meet Timestamp requirements by establishing a trusted digital signing time and ensuring the integrity of PDF data. In Europe, the eIDAS Regulation specifies the following mandatory requirements for advanced electronic signatures: With LTV, users can meet all these requirements and more! LTV in Security and Information Protection Digital signatures are one of the most effective tools for ensuring the integrity of electronic documents. The technology is standardized for use anytime and anywhere, and is recognized by private organizations, governments, and authorities around the world. LTV technology provides users with an additional layer of security through a historical chain of digital signature verification, supported by Timestamps and associated validation mechanisms. SAVYINT offers a comprehensive suite of solutions that fully supports LTANS/LTV long-term archiving standards, as well as standards for digital signatures and remote digital signing, including eIDAS 2.0 and NIS2, ensuring the ability to archive documents over the long term or permanently. Including the following solutions: Contact us today for expert consultation HERE!
Understanding Long-Term Validation (LTV) in Digital Signatures
To standardize formats and ensure verifiability, the European Telecommunications Standards Institute (ETSI) has issued a series of foundational standards for digital signature formats. One of the most important is TS 102 778, which provides guidelines for applying the ISO 32000-1 standard to PDF files. This standard is also known as PDF Advanced Electronic Signatures (PAdES). The PAdES standard was developed to ensure that digitally signed electronic documents can be stored, retrieved, and used for decades. At any point in the future, even as technology advances dramatically, users must still be able to validate electronic documents – particularly the validity of digital signatures at the time of signing. This requirement laid the foundation for the development of Long-Term Validation (LTV) technology. The introduction of the PAdES signature standard marked the standardization of advanced digital signature formats for PDF files, enabling long-term storage and validation. With Long-Term Validation (LTV) technology, the digital signing timestamp is recorded and stored directly within the electronic document. The LTV-enabled status is displayed in the digital signature parameters. Validation evidence is embedded directly in the electronic document, allowing the validity of the electronic record to be verified in the future without depending on the validity or revocation status of the digital certificate after signing. Since this evidence is stored within the digitally signed document, it is also authenticated and protected by the document’s digital signature, significantly minimizing the risk of errors or forgery. LTV technology is a valuable option for individuals, organizations, and businesses seeking to reduce their dependence on third-party systems and minimize future uncertainty regarding expired or revoked digital certificates. Applying LTV to Digital Signature Solutions Today, certain industries require the validity of a signature to be verifiable at the time of signing, making the adoption of advanced standards such as PAdES necessary. When Acrobat Reader or any other PDF software that supports digital signature validation opens a PDF document, it can readily validate the digital certificate used in the document-signing process without requiring separate digital signing applications provided by service providers. With LTV technology, signing-time data is stored directly in the document, allowing PDF software to validate the digital signature at the time of signing using the embedded timestamp information. As a result, PDF software can still verify the validity of the digital certificate at the time of signing, even if the original certificate has since expired or been revoked. For electronic documents that have not been digitally signed using LTV technology, PDF software such as Acrobat Reader may encounter difficulties validating the digital certificate associated with the digital signature. If the certificate has expired, Acrobat Reader will display a yellow warning to the user stating, “At least one signature has problems.” This warning means that Acrobat Reader cannot determine whether the digital certificate was valid at the time of signing. Savyint is one of the trusted providers of LTV digital signature solutions that fully comply with European and international standards. Contact us today for consultation HERE!
Comparing Digital Signatures With and Without Trusted Timestamps
Digital signatures on electronic documents help identify and authenticate signatories, ensure document integrity, and provide non-repudiation. So, what additional value does a digital signature offer when combined with a trusted Timestamp and Long-Term Validation (LTV) technology, and in which cases should this solution be used? Digital Signatures Ensure Signer Identification, Authentication, Document Integrity, and Non-Repudiation Paper-based documents bearing handwritten signatures and red seals are gradually becoming outdated in the face of new societal demands and challenges. Paper documents are inefficient because they depend on and are constrained by numerous factors, including printing and scanning speeds, printers, ink, and document delivery times. The same person’s handwritten signature may vary across documents and can be easily forged or used for fraudulent purposes, making verification and notarization difficult. Furthermore, paper documents are susceptible to tearing, alteration, and erasure, making their integrity difficult to guarantee. Therefore, adopting digital signature systems for individuals, organizations, and enterprises is a fundamental prerequisite and the first step toward comprehensive digital transformation. In legal terms, digital signatures have the same legal validity as handwritten signatures and seals. Electronic documents digitally signed in accordance with applicable regulations enable accurate identification and authentication of the signatory, ensure document integrity, and provide non-repudiation. A digital signature is intentionally created by its owner and is designed to prevent forgery or accidental creation through technical mechanisms provided by trust service providers and digital signature solutions. Digital signatures provide a trusted foundation for document digitization and the creation of electronic documents. Digital Signatures With and Without Trusted Timestamps and LTV With digital signatures that do not include a trusted timestamp, the displayed signing time is based on the clock of the signing device or server. This time can be easily altered using simple tools, potentially exposing time-sensitive documents and records—such as financial, banking, and securities transactions; purchase and sale contracts; electronic medical records; and certificates of intellectual property ownership or copyright—to forgery and fraud. In the event of a dispute, it may therefore be difficult to establish the exact time at which a document was signed and whether the digital signature was valid at that time. In particular, when a digital certificate has expired, verifying the signing time and document integrity may become difficult or impossible if the necessary validation data has not been preserved. As a result, the document may lose its evidentiary value if its authenticity and the validity of the signature at the time of signing cannot be established. This poses a risk to organizations that rely solely on digital signatures without trusted timestamps, especially when handling sensitive documents for which the signing time and the validity of the digital signature at that time must be proven. Digital signatures combined with trusted Timestamping and Long-Term Validation (LTV) provide enhanced integrity protection for your electronic documents, helping preserve the evidence needed for long-term validation. These include: Documents for which the legal validity of a digital signature at the time of signing is particularly important and for which trusted timestamping may be necessary, include: Explore Savyint Qualified Timestamp – a trusted timestamping service for electronic documents, HERE!
Savyint and SAVIS Advance Digital Trust for the Media Industry in Vietnam
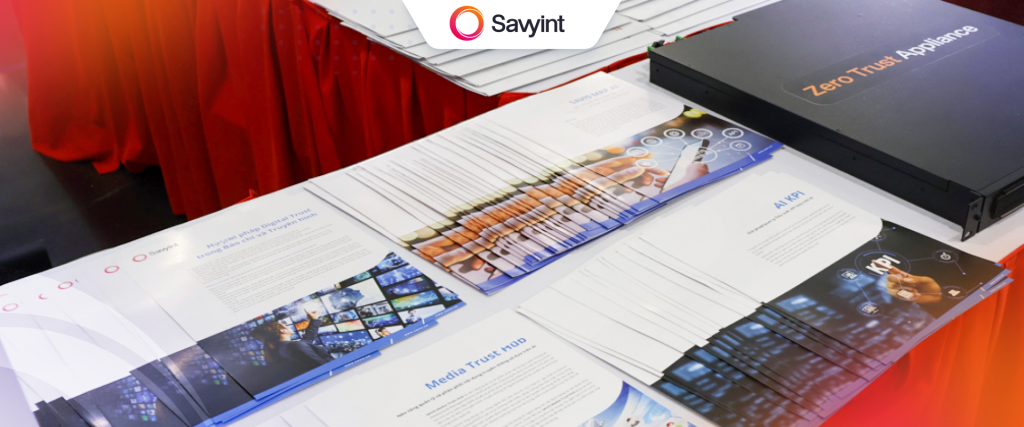
On October 9, at the exhibition “VTV – From Traditional Television to a Digital Media Organization: Audience-Centric, Data-Driven and AI-Powered,” organized by Vietnam Television (VTV), Savyint and its partner in Vietnam, SAVIS, showcased a modern suite of AI-powered solutions built on Zero Trust architecture and designed to be post-quantum cryptography-ready for VTV’s digital platforms. As one of the key activities marking Vietnam’s National Digital Transformation Day 2026, the exhibition brought together leading technology companies showcasing solutions for the television and media industries. In his opening remarks, Mr. Đinh Đắc Vĩnh, Deputy Director General of Vietnam Television, stated that the exhibition is one of VTV’s practical annual initiatives, contributing to the effective implementation of Politburo Resolution No. 57-NQ/TW on breakthroughs in science and technology development, innovation and national digital transformation, as well as VTV’s own digital transformation program. In recent years, advanced technologies such as AI and cloud computing have had a significant impact on the television industry, creating numerous opportunities to automate business processes, improve production efficiency, analyze data and personalize viewer experiences. The exhibition’s theme also addresses a key challenge facing broadcasters today: how to make emerging technologies more accessible and apply them more effectively. Supporting the digital transformation of the television industry, SAVIS introduced an ecosystem of solutions combining AI and Zero Trust architecture with post-quantum cryptography readiness. The ecosystem aims to achieve three key objectives: optimizing content production and distribution, maximizing the value of data resources, and building a secure and trusted digital environment, ultimately strengthening national digital sovereignty. AI and data are driving innovation, but a digital media ecosystem can operate sustainably only when all participating entities are authenticated, data is protected, and access rights are appropriately controlled. Together with SAVIS, a leading provider of Digital Trust solutions, Savyint introduced an ecosystem of platforms designed to ensure cybersecurity and information security for press and television organizations: All these platforms incorporate post-quantum cryptography (PQC) algorithms, including ML-KEM, ML-DSA and SLH-DSA, enabling flexible cryptographic transitions while supporting compliance with stringent data security and privacy requirements in Vietnam and internationally, including GDPR, PCI DSS, eIDAS 2.0 and PSD3. With an ecosystem combining AI, Digital Trust, Zero Trust and post-quantum cryptography, Savyint and SAVIS aim to support Vietnam Television and other television and media organizations in Vietnam and across the region in modernizing operations, maximizing the value of data, protecting intellectual property and strengthening cybersecurity capabilities. Some snapshots from the event:
Vietnam: Personal Data Security When Integrating with VNeID – What Should Businesses Do?
In Vietnam, connecting to and verifying information through the VNeID application has officially become a core form of digital identification, serving as the “digital identity” of each citizen in the electronic environment. However, as identity data is shared and utilized in the digital environment, businesses and organizations must also ensure that user data is properly managed and used. 1. Personal data protection: From “recommendation” to “mandatory requirement” Effective from January 1, 2026, the Personal Data Protection Law No. 91/2025/QH15 establishes a new legal framework for the collection, processing, and protection of personal data. Subsequently, Decree No. 320/2026/ND-CP, effective from September 28, 2026, further requires the connection and use of electronic identification and authentication across multiple sectors. Specifically: However, authentication through VNeID does not mean that organizations have the right to use all citizens’ data for every purpose. Under Vietnam’s Personal Data Protection Law, users have the right to know and request transparency regarding: The measures used to protect data against unauthorized access, use, or disclosure. Therefore, businesses and organizations also need to implement the necessary platforms and systems to safeguard users’ rights regarding the sharing of personal data, while supporting record-keeping and reporting when required. 2. Legal compliance needs to be translated into technical controls Personal data protection cannot stop at internal procedures or written policies. Vietnam’s personal data protection regulations have established clearer requirements regarding organizational responsibilities in cases involving personal data breaches and cybersecurity incidents. Specifically, the 2025 Personal Data Protection Law together with Decree No. 330/2026/ND-CP provides for administrative penalties in the areas of cybersecurity and personal data protection. Depending on the nature and severity of the violation, organizations and individuals may face: The collection, storage, use, provision, or sharing of data for improper purposes, without an appropriate legal basis, or without adequate data protection measures may also expose organizations to unnecessary legal risks. 3. What should businesses and organizations do to ensure user data security when integrating with VNeID? When data generated through electronic identification and authentication is incorporated into business processes, the responsibility for protecting that data does not stop at the point of connection with VNeID. Companies and organizations need to establish end-to-end data control mechanisms covering data collection, transmission, processing, storage, sharing, and the destruction or deletion of data in accordance with applicable regulations. Businesses should: Proactively protecting users’ personal data is not only a legal requirement but also an opportunity for businesses to strengthen risk management, prevent fraud, and protect their long-term reputation. To meet the requirements for personal data protection, strong authentication, and traceability when integrating with VNeID, businesses need a security architecture capable of maintaining control throughout the entire data lifecycle. With more than 22 years of experience in cybersecurity and digital trust, SAVYINT provides a comprehensive Digital Trust & Cybersecurity ecosystem with solutions such as Multi-Factor Authentication (MFA), Strong Customer Authentication (SCA), FIDO2 Identity, Post Quantum Identity & Authentication, Transaction Signing, data encryption, Tokenization, and API Security. These solutions help businesses strengthen access control, protect sensitive data, and enhance their ability to meet requirements for data security, traceability, and regulatory compliance in Vietnam. Contact with SAVYINT experts HERE.
Vietnam Seeks to Elevate Electronic Identification and Authentication Regulations into Law
For many years, electronic identification in Vietnam has largely been viewed as a tool to support the delivery of administrative procedures in the digital environment. For most citizens, electronic identification has been closely associated with the VNeID application, digital driving licences, or access to online public services without the need to present physical documents. However, the proposals put forward by the Ministry of Public Security as part of the development dossier for the Law on Electronic Identification and Authentication indicate that the scope and ambition of this policy extend far beyond that. If approved by the National Assembly of Vietnam, the legislation would not merely govern electronic identification accounts or the VNeID application. More broadly, the draft law seeks to establish a national digital identity infrastructure in which not only individuals but also organizations, goods, assets, data, software, locations, transactions, and other entities within the digital economy can be identified, authenticated, and traced in the electronic environment. This represents an important shift in national governance — from traditional administrative management toward data-driven governance in the digital age. Electronic Identification Is Becoming Essential National Infrastructure Globally, electronic identification and authentication are increasingly regarded as core infrastructure for the digital economy. The European Union is implementing the European Digital Identity Framework (eIDAS 2.0) alongside the European Digital Identity Wallet, enabling citizens to use a unified digital identity when conducting transactions across member states. Estonia has long served as a model for digital government, with almost all public services operating on the basis of its electronic identification system. Singapore has developed the Singpass ecosystem to serve both the public and private sectors, spanning banking, insurance, real estate, and other services. Meanwhile, India operates Aadhaar with more than 1.4 billion digital identities, widely regarded as the world’s largest electronic identification system. The common thread across these models is that electronic identification is no longer viewed as a standalone technological utility. Instead, it has become an operational foundation for digital government, the digital economy, and digital society. Current international trends are moving even further beyond human identification. The European Union is implementing the Digital Product Passport, under which each product is assigned a unique electronic identifier to support traceability and lifecycle management. New international standards are also expanding the scope of identification to goods, assets, data, devices, applications, and many other types of entities in the digital environment. It is against this backdrop that the Ministry of Public Security considers it necessary for Vietnam to establish a legal framework with greater legal authority, enabling the country to keep pace with global developments and meet the requirements of national digital transformation. Regulations Are No Longer Sufficient for the Next Stage of Development After more than three years of implementing Decree No. 59/2022/ND-CP and Decree No. 69/2024/ND-CP, Vietnam’s national electronic identification system has achieved notable results. However, according to the Ministry of Public Security, Vietnam has now moved beyond the initial stage of electronic identification. Previously, the primary focus was on establishing digital identities for citizens and organizations. Today, the scope of governance requirements is considerably broader. In the digital environment, identifying people alone is no longer sufficient. The State needs the ability to identify vehicles, goods, locations, data, software, digital assets, and many other types of objects to support governance, transactions, and the development of the digital economy. Meanwhile, regulations relating to identification are currently scattered across multiple laws and subordinate legal instruments, including the Law on Identification, the Law on Electronic Transactions, the Law on Data, the Law on Digital Technology Industry, and various sector-specific regulations. This fragmentation creates significant challenges. For state management agencies, the absence of a unified legal framework limits the ability to ensure data interoperability across ministries, sectors, and local authorities. For businesses, compliance with multiple authentication mechanisms increases both compliance costs and transaction costs. For citizens, repeatedly providing and verifying information — even when the data already exists within government systems — reduces the efficiency of the digital transformation process. The development of a unified law is therefore expected to establish a common “language” for Vietnam’s entire digital identity and data ecosystem. Legal Recognition of Digital Identity and Reduced Reliance on Physical Documents Another important driver behind the development of the law is the need to strengthen the legal foundation for the use of electronic documents. In recent years, VNeID has integrated various types of documents, including identity cards, driving licences, vehicle registration certificates, health insurance information, and other documents. However, the number of documents integrated into the system remains limited compared with practical needs. Many agencies and organizations still require citizens to present physical documents even when the relevant information has already been authenticated through electronic systems. This situation reflects a fundamental issue: current legislation does not yet provide sufficiently comprehensive legal recognition of digital identities and electronic documents. In the absence of a sufficiently strong legal basis, many agencies continue to adopt the safer approach of requiring paper – based documentation rather than relying entirely on electronic data. Accordingly, one of the key objectives of the draft law is to establish clear legal status for digital identities, electronic documents, and electronic authentication results. If implemented effectively, this could provide the foundation for significantly reducing administrative paperwork, lowering compliance costs, and shortening the time required to process procedures for citizens and businesses. Electronic Identification Is Not Limited to Public Services A notable aspect of the draft legislation is that electronic identification is designed not only to support government operations but also to facilitate transactions within the private sector. In finance and banking, a unified electronic identification system could significantly reduce customer verification costs, improve the efficiency of eKYC processes, and help mitigate fraud. In e-commerce and logistics, the identification of goods and products could support traceability, combat counterfeit products, and enhance supply-chain trust. For data and digital assets, establishing electronic identities for data and intangible assets could provide a foundation for new data-driven business models. In other words, the draft law would not only affect public administration but
From Open Banking to Open Finance and Open Data
The Open Banking ecosystem is expanding rapidly, bringing significant and positive changes to the global financial landscape. The world is now ready to witness the next chapters in the evolution of Open Finance and Open Data. In fact, Open Banking emerged somewhat unexpectedly. In the UK, as Fintech companies began entering the retail payments market, there were initially no specific regulations governing how these parties should collaborate or operate within the ecosystem. A study conducted by the UK Competition and Markets Authority (CMA) found that the UK retail banking sector was highly concentrated, with limited competition. These findings provided a major impetus for the introduction of Open Banking regulations and similar initiatives worldwide, aimed at enhancing competition and driving economic growth. This led to the emergence of Open Banking, with its principles and requirements formally established under the European Parliament’s PSD2 Directive and, more recently, the proposed PSD3 framework. Key roles were also clearly defined, including Account Information Service Providers (AISPs), which aggregate users’ financial data from multiple accounts, and Payment Initiation Service Providers (PISPs), which enable payment services across accounts. The emergence of Open Banking has encouraged banks to invest in API technology and establish partnerships with Fintech organizations across Europe. Nordic banks were among the earliest and most enthusiastic adopters of this model. Digital Identity as an Enabler of Open Finance and Open Data The Nordic countries provide a compelling example of how digital identity can be adopted in banking for commercial purposes. As digital identity solutions become widely used across the region, they help accelerate customer authentication and streamline digital financial services. This has enabled Fintech companies not only to compete with traditional banks, but also to challenge credit and debit card providers, whose services have traditionally faced limitations in online customer information management. Beyond authentication, digital identity provides a trusted foundation for Open Finance and Open Data. By enabling secure identification, reliable authentication and consent-based data sharing, digital identity solutions can help users access financial services across multiple providers while maintaining control over their personal information. Integrated with secure APIs and consent management platforms, digital identity can support trusted data exchange among banks, Fintech companies and other authorized third parties, paving the way for more connected, interoperable and user-centric financial ecosystems. Open Data Enables Competition and Drives Innovation Following its implementation and widespread adoption, Open Banking has developed more rapidly than initially anticipated. Today, users can authorize banks to share their transaction histories, identification images and other relevant information with other banks or third-party providers of their choice. They can also switch accounts, apply for loans or obtain credit cards from new providers with greater ease. In addition, users can manage their financial histories through a single platform, eliminating the need to switch between multiple applications. This transformation is gaining momentum as new players enter the ecosystem. In the future, organizations outside the financial sector will also leverage Open Data to deliver highly personalized products and services, while allowing users to retain control over their own data. These new market participants will make it easier for users to discover and access services that meet their specific needs. Ultimately, services that significantly reduce time and costs will be well positioned to attract and retain users. Open Data – An Opportunity for Early Movers From the perspectives of regulators and users alike, the transition to Open Banking and Open Finance is not something that can be achieved overnight. It requires a continuous, long-term process. Greater attention will also be needed as new technological initiatives around Open Data emerge. For Open Data to drive meaningful and positive change, clear regulatory frameworks and legal standards are essential. This requires concerted efforts from regulatory authorities, as well as closer international cooperation to establish common standards and requirements for secure, compliant data exchange across borders. In conclusion, the world is witnessing the continued growth of Open Banking and the benefits it brings. It is now time to set the next goals for the era of Open Finance and Open Data. While this transformation will take time, it will serve as a powerful catalyst for global economic and technological development. SAVYINT – Comprehensive Open Banking Solutions SAVYINT provides a comprehensive Open Banking solution ecosystem, encompassing data management, Digital Identity and trusted digital services. Backed by more than 20 years of experience in the Banking and Financial Services sector, SAVYINT has successfully deployed solutions for leading banks and major organizations across Vietnam and Southeast Asia (SEA). The solution portfolio includes: Contact us today to consult with our leading Open Banking experts HERE!